We use cookies to understand how you use our site and to improve your experience.
This includes personalizing content and advertising.
By pressing "Accept All" or closing out of this banner, you consent to the use of all cookies and similar technologies and the sharing of information they collect with third parties.
You can reject marketing cookies by pressing "Deny Optional," but we still use essential, performance, and functional cookies.
In addition, whether you "Accept All," Deny Optional," click the X or otherwise continue to use the site, you accept our Privacy Policy and Terms of Service, revised from time to time.
You are being directed to ZacksTrade, a division of LBMZ Securities and licensed broker-dealer. ZacksTrade and Zacks.com are separate companies. The web link between the two companies is not a solicitation or offer to invest in a particular security or type of security. ZacksTrade does not endorse or adopt any particular investment strategy, any analyst opinion/rating/report or any approach to evaluating individual securities.
If you wish to go to ZacksTrade, click OK. If you do not, click Cancel.
CRWV Q3 Earnings Impress, Outlook Raised: How to Play the Stock Now?
Read MoreHide Full Article
Key Takeaways
CoreWeave's Q3 revenue jumped 168% year over year to $3.66 billion, while adjusted EBITDA rose 169%.
CoreWeave raised 2026 revenue guidance to $13-$13.3 billion and reported a $132.5 billion backlog.
More than $47 billion in debt, rising interest costs and $37-$39 billion in capex weigh on profitability.
CoreWeave, Inc. (CRWV - Free Report) described the third quarter as a breakout quarter, with revenue increasing by more than $1 billion sequentially, improved adjusted operating margins, expanding infrastructure capacity and stronger customer commitments. It reported revenue of $3.66 billion, up 168% year over year, highlighting the company's ability to convert AI infrastructure demand into business growth rapidly.
CoreWeave’s adjusted operating income rose to $379 million, achieving a 10% margin versus 5% in the previous quarter. Adjusted EBITDA surged 169% year over year to $2.3 billion, with a 62% margin. However, the company reported a $709 million GAAP net loss, while net interest expense climbed to $846 million, highlighting the high financing costs of its aggressive expansion. Overall, improving margins signal stronger operating leverage, but GAAP profitability remains elusive.
In the past month, CRWV shares have plunged 14% compared with the Zacks Internet-Software Market’s fall of 9.5%. The stock has underperformed the Zacks Computer & Technology sector and the S&P 500 Composite, which dipped 9% and 2.3%, respectively, over the same period. Its key competitors include Nebius Group N.V. (NBIS - Free Report) and Microsoft (MSFT - Free Report) . MSFT and NBIS have lost 2% and 30.9%, respectively, in the past month.
Image Source: Zacks Investment Research
CRWV’s expanding relationships with leading AI companies, investments in next-generation NVIDIA (NVDA - Free Report) infrastructure and international expansion further strengthen its position in the rapidly evolving AI cloud market. For investors, the key question is now whether CoreWeave's accelerating growth justifies its valuation and whether the stock remains an attractive buying opportunity after its strong performance.
Infrastructure Expansion Strengthens CRWV's Competitive Position
CoreWeave added more than 200 MW of active power capacity, bringing its total active power to over 1.7 GW. This represents a doubling of its active infrastructure footprint since the beginning of 2026. Total contracted power increased by more than 900 MW to over 4.6 GW. Active power represents infrastructure capacity already available for operations, while contracted power reflects secured future capacity that may require additional development before becoming operational.
CoreWeave also expanded its international presence, with more than 1.3 GW of contracted power across international markets, including India, Indonesia and Spain. This international expansion creates opportunities to serve customers seeking geographically distributed computing capacity, lower-latency infrastructure and greater control over data residency. Management expects active power to exceed 1.85 GW by the end of 2026, indicating that infrastructure deployment remains a major operational priority.
Another encouraging development involved the deployment of NVIDIA's next-generation Vera Rubin NVL72 infrastructure, with initial production workloads for Cognition delivering 4.8 times higher token throughput than GB200 NVL72. The company also announced support for NVIDIA Vera CPUs, designed for AI agent workloads. These developments could strengthen CoreWeave’s competitive edge as demand for AI inference, agentic AI and advanced computing infrastructure grows.
CoreWeave is also strengthening its enterprise ecosystem. In September, it introduced Physical AI Field Engineering, an initiative that places its engineers alongside customer teams to help transform proprietary data into production-ready AI applications. It also established the CoreWeave Partner Network, bringing together technology providers across observability, security and data infrastructure. Initial partners include Grafana Labs, CrowdStrike and VAST Data. These partnerships could make CoreWeave Cloud more attractive to enterprises looking for integrated AI infrastructure rather than standalone GPU computing capacity.
CRWV’s Raised View Signals Stronger AI Infrastructure Demand
A key factor for CRWV stock has been management's decision to raise its full-year 2026 outlook. CoreWeave now expects 2026 revenue of $13 billion to $13.3 billion compared with its previous range of $12.4-$13.2 billion. Adjusted operating income guidance increased to $1.28 billion-$1.38 billion from $960 million-$1.15 billion. It also raised its year-end annualized revenue run-rate target to $20-$21 billion, up from $18.5-$19.5 billion.
The company raised its adjusted operating income guidance by 26% at the midpoint compared with its previous outlook. This suggests that the business is achieving better operating efficiency as its infrastructure footprint expands. Another key metric is its $132.5 billion revenue backlog, which increased 138% year over year. This provides substantial visibility into future contracted revenue, although conversion depends on infrastructure delivery, service availability and contract execution.
CRWV also expects approximately $9 billion in customer prepayments and deposits over the next three months. These payments can help finance infrastructure expansion and improve liquidity, although they should not be confused with recognized revenue or operating profit.
Elevated Debt & Capex Pose Bigger Risk for CRWV
Despite its strong growth outlook, CoreWeave's financial structure deserves careful consideration. The company's infrastructure expansion requires enormous capital investment. Management now expects 2026 capital expenditure of $37 billion to $39 billion, reflecting plans to deploy infrastructure and deliver capacity to customers sooner than expected. Its debt was approximately $47 billion at the end of September 2026.
Heavy reliance on debt and capital markets also exposes the company to rising interest rates and tighter financing conditions. Quarterly net interest expense totaled $846 million, and management expects fourth-quarter interest expense of $1.05-$1.15 billion. These figures explain why strong revenue growth has not yet translated into positive GAAP earnings. Additional concerns include macroeconomic and regulatory uncertainty, potential industry oversupply, rising operating expenses, customer and infrastructure concentration and limited visibility beyond 2027. These factors could pressure margins, cash flow and long-term profitability.
CoreWeave's long-term success will depend not only on securing customer contracts but also on converting infrastructure investments into sustainable operating cash flow.
CRWV’s Estimate Revision Trend
CRWV’s estimates are being revised downward. The Zacks Consensus Estimate for its earnings for 2026 has been revised south 2.4% over the past 60 days.
Image Source: Zacks Investment Research
Valuation Expectations
CRWV stock seems attractive, as suggested by the Value Style Score of B. In terms of Price/Book, CRWV shares are trading at 5.17X, slightly higher than the Internet Software industry’s 4.9X, but it could mean more risk than opportunity.
p> Image Source: Zacks Investment Research
NBIS and MSFT shares are trading at multiples of 3.15X and 8.26X, respectively.
CoreWeave's third-quarter results highlight robust demand for specialized AI cloud infrastructure. Revenue increased 168% year over year, adjusted operating income reached $379 million, and the company raised its full-year revenue and profitability outlook. Its $132.5 billion backlog and expanding infrastructure footprint also provide long-term growth opportunities. However, the investment case is not without risks. Approximately $47 billion in debt, rising interest expenses, substantial capital expenditure and potential equity dilution make CRWV a relatively high-risk investment.
CoreWeave remains an attractive long-term AI infrastructure growth opportunity, but shareholders can consider holding the stock now while monitoring backlog conversion and cash flow generation.



 View the Zacks #1 Rank List


Image: Shutterstock
CRWV Q3 Earnings Impress, Outlook Raised: How to Play the Stock Now?
Key Takeaways
CoreWeave, Inc. (CRWV - Free Report) described the third quarter as a breakout quarter, with revenue increasing by more than $1 billion sequentially, improved adjusted operating margins, expanding infrastructure capacity and stronger customer commitments. It reported revenue of $3.66 billion, up 168% year over year, highlighting the company's ability to convert AI infrastructure demand into business growth rapidly.
CoreWeave’s adjusted operating income rose to $379 million, achieving a 10% margin versus 5% in the previous quarter. Adjusted EBITDA surged 169% year over year to $2.3 billion, with a 62% margin. However, the company reported a $709 million GAAP net loss, while net interest expense climbed to $846 million, highlighting the high financing costs of its aggressive expansion. Overall, improving margins signal stronger operating leverage, but GAAP profitability remains elusive.
In the past month, CRWV shares have plunged 14% compared with the Zacks Internet-Software Market’s fall of 9.5%. The stock has underperformed the Zacks Computer & Technology sector and the S&P 500 Composite, which dipped 9% and 2.3%, respectively, over the same period. Its key competitors include Nebius Group N.V. (NBIS - Free Report) and Microsoft (MSFT - Free Report) . MSFT and NBIS have lost 2% and 30.9%, respectively, in the past month.
Image Source: Zacks Investment Research
CRWV’s expanding relationships with leading AI companies, investments in next-generation NVIDIA (NVDA - Free Report) infrastructure and international expansion further strengthen its position in the rapidly evolving AI cloud market. For investors, the key question is now whether CoreWeave's accelerating growth justifies its valuation and whether the stock remains an attractive buying opportunity after its strong performance.
Infrastructure Expansion Strengthens CRWV's Competitive Position
CoreWeave added more than 200 MW of active power capacity, bringing its total active power to over 1.7 GW. This represents a doubling of its active infrastructure footprint since the beginning of 2026. Total contracted power increased by more than 900 MW to over 4.6 GW. Active power represents infrastructure capacity already available for operations, while contracted power reflects secured future capacity that may require additional development before becoming operational.
CoreWeave also expanded its international presence, with more than 1.3 GW of contracted power across international markets, including India, Indonesia and Spain. This international expansion creates opportunities to serve customers seeking geographically distributed computing capacity, lower-latency infrastructure and greater control over data residency. Management expects active power to exceed 1.85 GW by the end of 2026, indicating that infrastructure deployment remains a major operational priority.
Another encouraging development involved the deployment of NVIDIA's next-generation Vera Rubin NVL72 infrastructure, with initial production workloads for Cognition delivering 4.8 times higher token throughput than GB200 NVL72. The company also announced support for NVIDIA Vera CPUs, designed for AI agent workloads. These developments could strengthen CoreWeave’s competitive edge as demand for AI inference, agentic AI and advanced computing infrastructure grows.
CoreWeave is also strengthening its enterprise ecosystem. In September, it introduced Physical AI Field Engineering, an initiative that places its engineers alongside customer teams to help transform proprietary data into production-ready AI applications. It also established the CoreWeave Partner Network, bringing together technology providers across observability, security and data infrastructure. Initial partners include Grafana Labs, CrowdStrike and VAST Data. These partnerships could make CoreWeave Cloud more attractive to enterprises looking for integrated AI infrastructure rather than standalone GPU computing capacity.
CRWV’s Raised View Signals Stronger AI Infrastructure Demand
A key factor for CRWV stock has been management's decision to raise its full-year 2026 outlook. CoreWeave now expects 2026 revenue of $13 billion to $13.3 billion compared with its previous range of $12.4-$13.2 billion. Adjusted operating income guidance increased to $1.28 billion-$1.38 billion from $960 million-$1.15 billion. It also raised its year-end annualized revenue run-rate target to $20-$21 billion, up from $18.5-$19.5 billion.
The company raised its adjusted operating income guidance by 26% at the midpoint compared with its previous outlook. This suggests that the business is achieving better operating efficiency as its infrastructure footprint expands. Another key metric is its $132.5 billion revenue backlog, which increased 138% year over year. This provides substantial visibility into future contracted revenue, although conversion depends on infrastructure delivery, service availability and contract execution.
CoreWeave Inc. Price and Consensus
CoreWeave Inc. price-consensus-chart | CoreWeave Inc. Quote
CRWV also expects approximately $9 billion in customer prepayments and deposits over the next three months. These payments can help finance infrastructure expansion and improve liquidity, although they should not be confused with recognized revenue or operating profit.
Elevated Debt & Capex Pose Bigger Risk for CRWV
Despite its strong growth outlook, CoreWeave's financial structure deserves careful consideration. The company's infrastructure expansion requires enormous capital investment. Management now expects 2026 capital expenditure of $37 billion to $39 billion, reflecting plans to deploy infrastructure and deliver capacity to customers sooner than expected. Its debt was approximately $47 billion at the end of September 2026.
Heavy reliance on debt and capital markets also exposes the company to rising interest rates and tighter financing conditions. Quarterly net interest expense totaled $846 million, and management expects fourth-quarter interest expense of $1.05-$1.15 billion. These figures explain why strong revenue growth has not yet translated into positive GAAP earnings. Additional concerns include macroeconomic and regulatory uncertainty, potential industry oversupply, rising operating expenses, customer and infrastructure concentration and limited visibility beyond 2027. These factors could pressure margins, cash flow and long-term profitability.
CoreWeave's long-term success will depend not only on securing customer contracts but also on converting infrastructure investments into sustainable operating cash flow.
CRWV’s Estimate Revision Trend
CRWV’s estimates are being revised downward. The Zacks Consensus Estimate for its earnings for 2026 has been revised south 2.4% over the past 60 days.
Image Source: Zacks Investment Research
Valuation Expectations
CRWV stock seems attractive, as suggested by the Value Style Score of B. In terms of Price/Book, CRWV shares are trading at 5.17X, slightly higher than the Internet Software industry’s 4.9X, but it could mean more risk than opportunity.
p>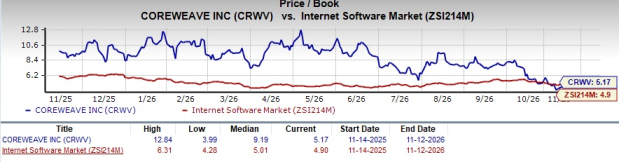
Image Source: Zacks Investment Research
NBIS and MSFT shares are trading at multiples of 3.15X and 8.26X, respectively.
How to Play CRWV Stock After Q3 Results
CRWV currently carries a Zacks Rank #3 (Hold). You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
CoreWeave's third-quarter results highlight robust demand for specialized AI cloud infrastructure. Revenue increased 168% year over year, adjusted operating income reached $379 million, and the company raised its full-year revenue and profitability outlook. Its $132.5 billion backlog and expanding infrastructure footprint also provide long-term growth opportunities. However, the investment case is not without risks. Approximately $47 billion in debt, rising interest expenses, substantial capital expenditure and potential equity dilution make CRWV a relatively high-risk investment.
CoreWeave remains an attractive long-term AI infrastructure growth opportunity, but shareholders can consider holding the stock now while monitoring backlog conversion and cash flow generation.